Albert: Budgeting and Banking
Albert - Budgeting & BankingFinanceVerified
- 37.74K Reviews
- 4.5
- Downloads
- 5,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
Before I hand a budgeting app access to my financial routine, I want to know what it will actually help me do: notice where money is going, make a realistic plan, and follow through without turning every purchase into a chore. Albert: Budgeting and Banking brings budgeting, banking, saving, and investing into one finance app, and its appeal is the chance to connect those decisions rather than manage them in separate places. I find that useful for someone who wants a clearer view of everyday money, but it works best when you’re comfortable linking an account and checking the app’s picture against your own priorities.
Start with the money you already have
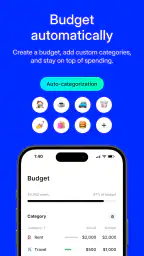
The most practical way to begin is not by setting an ambitious savings target. It is by looking at the activity the app organizes and asking whether the categories match how you think about your spending. Automatic categorization can save the tedious work of entering each purchase, but it is still worth reviewing the results: a miscategorized expense can make a budget feel inaccurate even when the transaction itself is correct. I’d use the first few check-ins to learn what the app is showing before treating its view as a finished financial plan.
That distinction matters if your income or expenses vary. A month with an annual bill, a trip, or an unusually large grocery shop can make ordinary spending look misleading. Rather than reacting to one alert, I’d compare the pattern with what is normal for me and adjust my habits based on repeated signals. This is where an automated overview can help without replacing judgment: it reduces the tracking burden, while I remain responsible for deciding which expenses are essential and which can change.
Turn a spending overview into a routine
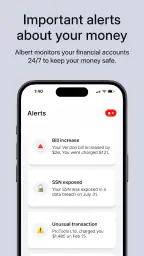
A useful everyday workflow is to check in after income arrives, scan the recent transactions, and decide what needs attention before the next round of bills. If a category is climbing, I can make a small adjustment for the coming week instead of waiting until month-end to find out that the budget no longer fits. The app’s spending insights and alerts are most valuable as prompts for that conversation with myself, not as commands to spend or save a particular amount.
For example, if I’m trying to put money aside for a vacation while still covering regular expenses, I’d first look at my recent activity and choose a target that leaves room for necessary costs. Then I’d watch the account through the week and reconsider the target if an unexpected bill appears. That is a more sustainable use of an automated tool than assuming every suggested transfer is harmless. The best result is not simply a growing balance; it is a saving habit that doesn’t force me to rely on credit or miss an important payment.
Let automation help, but keep a hand on the controls
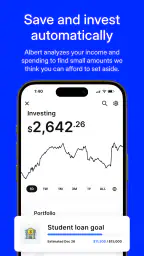
The automatic savings feature is designed to assess income and spending patterns before moving small amounts into savings. That can suit people who find manual transfers easy to postpone. I would still check the timing and the available balance, particularly around bills or income that arrives irregularly. Automation is convenient only when it fits the cash-flow rhythm of the person using it; a transfer that feels minor on an ordinary week may be poorly timed when several expenses land together.
The same cautious approach applies to the Safety Net. Building an emergency cushion is a sensible goal, but I’d treat it as a gradual reserve rather than money that is available for casual spending. If I have a near-term expense, I would consider that before relying on automatic saving. This makes the feature more useful: it supports preparation for surprises without encouraging me to confuse a savings balance with spare cash.
Other Stories to Read




When guidance and investing enter the picture
The app also reaches beyond tracking and saving. Its Genius service offers text-based access to financial experts, which may be appealing when I have a specific question and want guidance tied to my circumstances. That is different from simply reading a general budgeting tip, but it is also a premium service, so anyone trying to keep costs down should decide whether that kind of support is worth paying for before relying on it. I’d approach a conversation with a clear question and relevant context, then take time to weigh the answer rather than treating any single response as a substitute for my own research.
Investing is another step in the workflow, and the app aims to make getting started less intimidating by presenting options based on risk preference. That simplicity can be helpful for a beginner who wants an accessible entry point. It is not a reason to invest money needed for rent, bills, or an upcoming purchase, though. I’d first make sure my short-term needs and emergency savings are accounted for, then consider whether the available choices make sense for my goals and comfort with risk. A person who wants detailed portfolio controls or a highly specialized investing setup may be better served by a dedicated investment platform.
For someone who currently checks a bank app, a spreadsheet, and a separate savings tool, the main trade-off is convenience versus control. Keeping everything together can make it easier to spot the relationship between spending and saving, while a spreadsheet offers more freedom to build custom categories and a bank’s own tools may be enough for someone who only needs balances and transactions. I see Albert as most helpful when I want a guided overview and simple routines, not when I want to engineer every part of a budget myself.
Where a connected workflow can snag
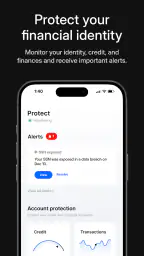
Account linking is the first meaningful point of friction. Sharing financial access can feel uncomfortable, even when an app presents itself as secure, and I would not rush through that decision just to reach the dashboard. I’d read the connection and privacy information in the app, use account security practices I’m comfortable with, and decide whether the convenience is worth the access involved. If I prefer not to connect accounts at all, a manual spreadsheet or a budgeting method based on reviewing statements may be a better fit.
There can also be a gap between a tidy spending summary and the decisions a household actually needs to make. Shared bills, cash purchases, reimbursements, and irregular income can require context that a transaction list alone does not provide. In those situations, I’d use the app as one input and keep a short note or separate plan for anything the automatic view cannot express clearly. That extra step is not a failure; it is a realistic boundary for automated categorization.
Availability is another consideration. Albert is described as a U.S.-only option, so it is not the right choice for someone managing finances abroad. Even within its intended audience, the best fit depends on how much guidance someone wants: a hands-off saver may appreciate automatic transfers, while a person who prefers to approve every move may find them less comfortable. I would also weigh the premium cost of Genius against how often I expect to use expert help, rather than assuming that every part of the experience is free.
How the app fits into a real financial routine
Right from the get-go, the app is super easy to navigate. The design is clean and modern, with a user-friendly interface that doesn’t overwhelm you with too much at once. Even the sign-up process felt like a breeze. I just had to link my bank account, and in no time, Albert was crunching numbers and giving me insights into my spending habits.
One thing I noticed was how the app categorized my spending automatically. No more manually entering every coffee purchase – Albert does it for you. It’s like having a personal accountant in your pocket, and honestly, who wouldn’t want that?
Features that Stand Out
The Albert app has some pretty nifty features that set it apart from other budgeting apps. For starters, the "Genius" feature is like having a financial advisor without the hefty fees. You can text "Geniuses" – real financial experts – and get advice tailored to your situation. I tried this out when I was unsure about how to start saving for a vacation, and the advice was spot on.
Another standout feature is the automatic savings tool. Albert analyzes your income and spending patterns to figure out how much you can afford to save. It then transfers small amounts to your savings account automatically. It’s a game-changer for someone like me who struggles to save consistently.
Let's not forget about the investment feature. If you’re looking to dip your toes into investing, Albert makes it simple. It offers a range of investment options based on your risk preference. I was impressed by how straightforward it was to get started.
Real-Life Application
What’s all this techy goodness without real-world application, right? I decided to test Albert over a month and see if it truly made a difference in my financial habits. Spoiler alert: it did. I became more aware of my spending, and the app’s alerts helped me cut down on unnecessary expenses.
One feature I really appreciated was the "Safety Net". It’s basically an emergency fund that the app helps you build. It felt reassuring to know I was slowly but surely building a cushion for unexpected expenses.
A routine like this is particularly useful for someone whose main difficulty is remembering to save, rather than someone who needs to construct a detailed plan from scratch. I’d check whether the automatic categories reflect my real habits, review alerts in context, and keep a separate note of any large one-off costs that could distort the month. That small amount of oversight helps turn the app’s convenience into a decision-making aid instead of an unquestioned scorecard.
Any Drawbacks?
While Albert: Budgeting and Banking is a fantastic tool, it’s not without its flaws. For one, the text-based Genius advice is part of a premium service, so if you’re on a tight budget, you might not want to spring for it. Also, the app is currently only available in the U.S., which could be a bummer if you’re living abroad.
Another thing to keep in mind is that linking your bank account might feel a bit daunting, but rest assured, Albert uses bank-level security to protect your information.
Albert is developed by Albert - Budgeting & Banking, and it is free to install, with an Everyone age rating. It has a 4.5 average from around 150,000 ratings, and more than 5 million installs. Those figures suggest it has reached a broad audience, but they cannot tell me whether its way of handling money will suit my own habits. I’d judge that by whether the overview makes me more deliberate without adding stress or encouraging transfers I cannot comfortably afford.
The app has been available since January 30, 2019, and its current version is 10.0.37, with Android 7.0 as the minimum operating system requirement. For a prospective user, the practical takeaway is to check compatibility before installing and then decide whether the combination of banking, budgeting, saving, and investing is useful enough to keep in a regular routine. A single app can reduce the friction of switching between tools, but it does not remove the need to check transactions, protect account access, or make choices that fit real-life obligations.
Who I’d recommend it to
I’d point a budgeting beginner toward Albert if they want an approachable way to see spending, build a saving habit, and explore investing without assembling several tools first. It may also suit someone who likes reminders and wants the option of asking a specific financial question through Genius. The strongest use case is a person who will open the app regularly, question what the numbers mean, and adjust the plan when life changes.
I would steer away from it if account linking is a firm boundary, if you live outside the U.S., or if you need granular controls that a customizable spreadsheet or specialist finance app handles better. It may also be a poor match if you want expert guidance but are unwilling to pay for a premium service, or if you prefer to approve every savings move yourself. Those are not minor preferences: they affect whether the workflow feels supportive or intrusive.
Conclusion
In the end, Albert: Budgeting and Banking is like having a financial guardian angel. It’s intuitive, comprehensive, and genuinely helps you get a handle on your finances. Whether you’re a budgeting novice or a seasoned saver, Albert offers tools that can help you achieve your financial goals. If you’re in the U.S. and looking for a way to simplify your financial life, I’d say give Albert a try. You might just find yourself wondering how you ever managed without it!
My recommendation comes with one qualification: let the app organize the picture, but keep yourself in charge of the decisions. Start by reviewing categories and alerts, then see whether automatic saving fits your cash flow before making it part of your routine. If that balance of guidance and personal oversight feels right, Albert can be a practical hub for everyday money. If you need complete customization or prefer not to connect your accounts, another approach will likely feel more comfortable.
Highlights
- User-friendly interface for easy navigation.
- Automatic savings feature simplifies budgeting.
- Customizable financial goals support.
- Real-time alerts for spending control.
- Fee-free cash advances available.
Limitations
- Limited investment options available.
- Customer support can be slow at times.
- Requires access to personal financial data.
- Some features need a subscription.
- No in-app bill payment option.
Frequently Asked Questions
01What is Albert: Budgeting and Banking and how does it work?
Albert is a financial management app designed to help users budget effectively, save money, and manage their banking needs. It provides personalized financial advice, tracks spending patterns, and offers automated savings options. Users can link their bank accounts to Albert, which then analyzes their financial data to provide insights and suggestions. The app aims to simplify personal finance and improve financial health.
02Is Albert: Budgeting and Banking secure to use?
Yes, Albert prioritizes user security by employing bank-level encryption to protect your financial data. It uses secure connection protocols and adheres to strict privacy standards to ensure your information is safe. Additionally, Albert does not store your bank login credentials, adding an extra layer of security. Users can feel confident that their financial data is protected while using the app.
03Does Albert: Budgeting and Banking charge any fees?
Albert offers a free version with basic features, but for more advanced tools, users can subscribe to Albert Genius, which operates on a pay-what-you-think-is-fair model starting at $4 per month. This subscription includes access to personalized financial advice and additional savings tools. Users can choose the tier that best fits their needs and budget.
04Can Albert help with saving money and budgeting?
Absolutely, Albert is designed to assist users in saving money and budgeting more effectively. It features Smart Savings, which automatically sets aside small amounts of money based on your spending habits. The app also offers budgeting tools that categorize expenses, track spending, and provide alerts to help users stay on top of their finances. These features work together to promote better financial habits.
05What devices support Albert: Budgeting and Banking?
Albert is available for both Android and iOS devices, making it accessible to a wide range of users. The app can be downloaded from the Google Play Store for Android devices and the Apple App Store for iOS devices. It is regularly updated to ensure compatibility with the latest operating systems and to introduce new features, providing a smooth user experience across platforms.


